Why has Kazakhstan's sugar industry been in turmoil for years?
Kazakhstan's sugar factories have failed to reach stable growth for a third straight year, while imports are gradually pushing domestic products out of the domestic market.
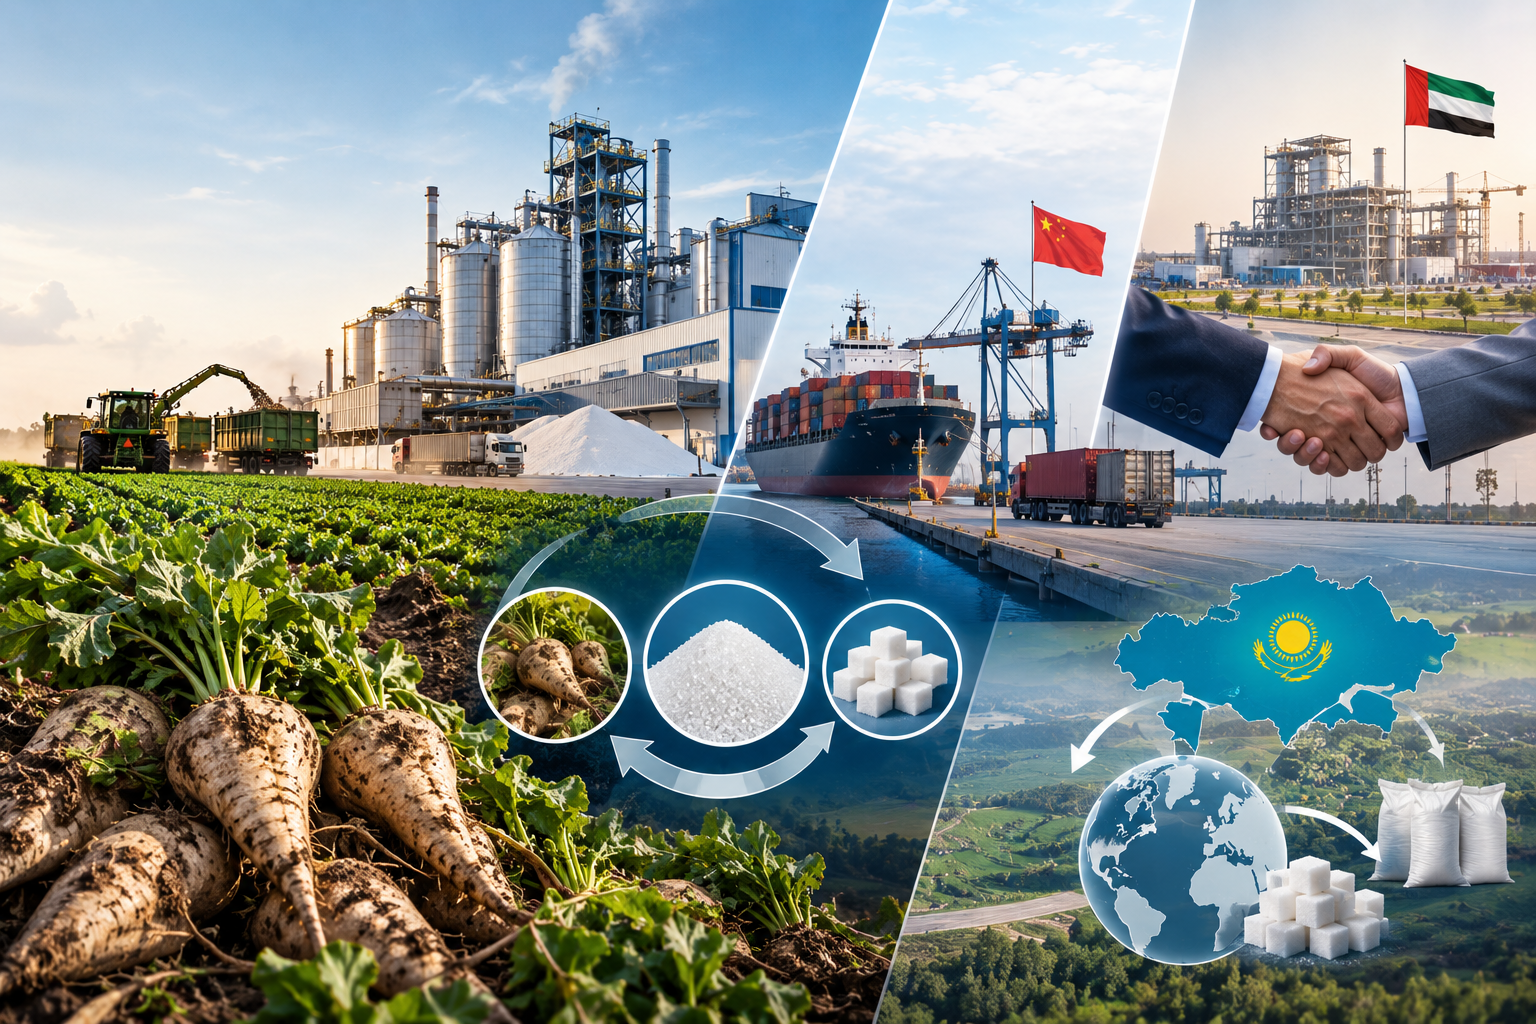
Right now, one of the world's largest sugar producers is entering the industry with investments worth hundreds of millions of dollars — a coincidence that deserves a detailed examination.
The gist in brief
- In the first half of 2026, Kazakhstan's sugar factories produced only 78,000 tonnes of product — 35.2% less than in the same period last year; domestic sales also fell (−13.7%), as did exports (−29%).
- The import share of the domestic market grew from 49.8% in 2022 to 70.4% in 2025 — domestic production has lost more than 20 percentage points of the market in three years.
- The 2025 sugar self-sufficiency target (68%) was not achieved in terms of production volume (174,200 tonnes instead of the planned 250,000), beet acreage (17,700 hectares instead of 38,000), or gross harvest (734,700 tonnes instead of 1.8 million).
- The key structural barrier is the gap between the raw material base and processing capacity: with a record beet harvest of 1.3 million tonnes in 2024, factories were able to accept only about 700,000 tonnes for processing, which forced farmers to cut plantings nearly in half the following year.

A vicious circle between field and factory
According to the Agency for the Protection and Development of Competition (AZRK), the logic of what is happening in the industry looks like a vicious circle. Farmers are expanding beet plantings, but factories physically cannot process the entire harvest in time — as happened in 2024, when out of 1.3 million tonnes harvested, only about 700,000 could be processed. In response, farmers sharply reduced planted areas the following season, and the gross harvest fell by 42.1%. At the same time, idle capacity was not loaded with compensating raw materials either: equipment for processing raw cane sugar was used at only 26.3% last year, while beet lines were used at 89.5%. It turns out that a shortage of raw materials and excess capacity exist simultaneously, just at different stages of the production chain.
What holds back farmers and processors
AZRK experts cite a whole list of problems at the level of individual farms: low technical equipment, failure to follow agricultural practices, insufficiently qualified personnel, poor quality of domestic seeds, and a chronic shortage of working capital. Processors have their own difficulties — worn-out equipment and incomplete capacity utilisation. Taken together, this means that even under favourable conditions the industry cannot quickly increase volumes: the weak link shows up either at the field level or at the factory level.
How this problem is solved in Europe
The European experience cited by AZRK experts is built on long-term contracts between agricultural producers and factories — a practice used in France, Germany, and Poland. The parties agree before sowing, fixing not the price itself but a pricing formula that takes into account all significant factors. This gives farmers predictability when planning expenses, and the entire chain transparency at every stage. An additional tool is food security monitoring systems for sugar, already in operation in the EU and India: the volumes that can be sent for export there are determined only after assessing domestic supply and forecasts for production and consumption. It is precisely this approach, according to AZRK specialists, that would help Kazakhstan limit the practice of re-exporting imported sugar to the detriment of priority supply to its own market.
A major investor bets on the same industry
Against this backdrop, the contrast with another story we followed this summer is especially striking: the Emirati company Al Khaleej Sugar — the world's largest autonomous sugar producer, controlling about 3% of the global refined sugar market — has begun construction of a plant in Konaev with $580 million in investments. The project envisages processing 500,000 tonnes of product per year based on local beet raw materials — from 65,000 to 100,000 hectares of planted area. The company's managing director specifically emphasised the water issue as a critical factor for the project's success and stated its readiness to engage specialised hydrology consultants. The decision to come to Kazakhstan coincided with a sharp rise in world sugar prices — El Niño threatens the sugarcane harvest in India, the world's second-largest producer, and white sugar futures have already exceeded $660 per tonne.
Two parallel realities of one industry
It turns out that Kazakhstan's sugar industry exists simultaneously in two logics. Domestic statistics record a chronic shortfall in planned targets, an imbalance between field and factory, and the loss of market share to imports. At the same time, a major international investor is betting specifically on Kazakhstan's beet potential — and doing so at a moment when the global sugar market is experiencing a deficit due to problems in tropical producing regions. Both pictures do not contradict each other: they describe the same industry with accumulated structural problems, but with simultaneously growing interest in its raw material potential from players ready to invest their own money and technology in solving those problems.
Author's conclusion
AZRK data show that efforts in recent years — increased state support, the inclusion of the sugar industry in the Comprehensive Plan for the Development of the Agro-Industrial Complex — have not yet reversed the trend: the self-sufficiency plan has not been fulfilled for any of the key indicators. The arrival of Al Khaleej Sugar does not solve these problems automatically — the new plant will have to go through the same constraints on water, personnel, and raw material logistics that are holding back existing Kazakh processors. But the scale of the investment and the fact that the project is built on local beet rather than imported raw sugar indicate that at least one major market player considers the industry's structural problems solvable — provided that more balanced relations are built between the raw material base and processing than Kazakh companies have managed so far.
Comments ()